 A buyer asks why revenue increased while cash fell. The owner knows the business had a busy year, but the answer is spread across an income statement, a receivables report, and a spreadsheet maintained outside the accounting system. Each document contains part of the explanation. None makes the full picture easy to follow.
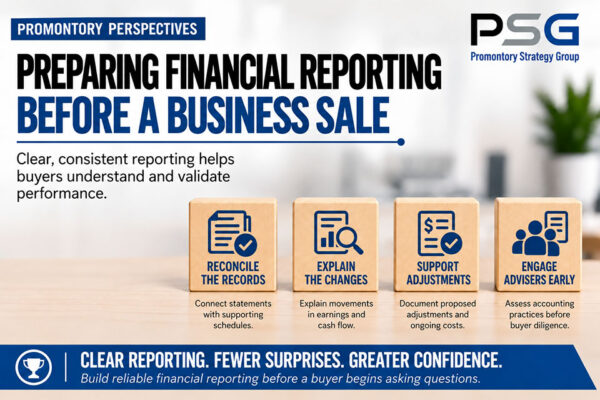
Preparing financial reporting before a business sale means closing those gaps before a transaction puts them under pressure. The objective is to make results traceable, explain meaningful changes, and separate what happened from what ownership expects next.
Start With the Questions Your Reports Cannot Yet Answer
Consider a hypothetical manufacturer whose annual revenue rose while its bank balance declined. The business may have bought inventory ahead of orders, waited longer for customers to pay, or spent cash on equipment. Those explanations have different implications, even though each could appear alongside higher sales.
An owner should be able to follow the explanation from the financial statements into supporting schedules. If collections slowed, the receivables aging should show where balances accumulated. If inventory increased, the records should distinguish stock intended for upcoming orders from items that have stopped moving.
This exercise can reveal a reporting problem before it becomes a sale-process problem. Perhaps the monthly statements exclude an entity included in the year-end accounts. Perhaps a department tracks costs differently from the accounting system. Resolve the difference with the company’s accountant and document how the figures connect.
PSG’s transaction preparation can help ownership put these questions in the context of a potential sale. The useful starting point is often the explanation you cannot yet support, rather than another spreadsheet added to the folder.
Build a Reporting Package That Can Be Followed
A well-organized package gives each document a job. Historical statements show reported performance. Supporting schedules explain balances and movements. Forecasts set out expectations, with assumptions visible. Keep those roles distinct so a reader can tell which figures are actual and which depend on future events.
For example, a month-by-month view of revenue and gross profit may reveal a margin change that an annual total hides. Before offering an explanation, check whether pricing, production costs, product mix, or the timing of recorded expenses contributed. Use the same reporting periods and definitions when comparing results.
Set a reporting cut-off and identify who owns each schedule. As new months close, update the package consistently rather than allowing several competing versions to circulate. A file that reconciled three months ago may no longer match the latest accounts.
The same discipline applies to proposed earnings adjustments. If ownership identifies a relocation expense as nonrecurring, retain the invoice and explain the event. Then account for any continuing costs at the new site. Removing an unusual expense without considering what replaced it can leave an incomplete picture of ongoing performance.
U.S. Bank’s valuation guidance identifies inconsistent records as a concern when buyers try to validate past performance. That makes the connection between statements, schedules, and explanations a practical preparation priority.
Use the Preparation Period to Fix the Routine
Reporting improvements are easier to assess when they have become part of normal operations. If a new month-end process produces cleaner information, give it time to work through actual reporting cycles. Document what changed and retain the connection to earlier periods.
There is no need to assume every business requires the same accounting engagement. Discuss the contemplated transaction and available records with the appropriate advisers. An audit, a review, a compilation, and transaction-focused financial diligence or “Quality of Earnings” review serve different purposes, and the scope should follow the questions that need answering.
According to Christopher Riegg of Promontory Strategy Group, “One gap I have seen repeatedly is the absence of regular outside accounting oversight, particularly in inventory-intensive businesses where inventory valuation, liability recognition, and the treatment of capital expenditures can materially affect reported earnings. Even when a lender does not require reviewed or audited financial statements, owners considering a transition should engage an independent accounting firm early to assess their practices and determine the appropriate level of financial reporting. Addressing these issues before a sale can reduce surprises during buyer diligence, strengthen confidence in reported results, and help protect the transaction’s economics.”
Why PSG for Financial Reporting Readiness?
An accountant may be helping the business close its books while ownership is deciding whether, when, and how to pursue a sale. PSG works at that connection between financial information and strategic decisions, helping privately held and family-owned businesses assess preparation priorities alongside their existing advisers.
Founded by Christopher Riegg, CFA, CPA, Promontory Strategy Group brings strategic and financial advisory experience to those discussions. For this work, the question is which reporting gaps could complicate ownership’s plans and what can reasonably be addressed before a process begins.
If preparing financial reporting before a business sale is on your agenda, start with one question your current reports struggle to answer. Talk with PSG about the available preparation period and the information needed to choose a practical next step.
Why Promontory Strategy Group?
Established by Christopher Riegg, CFA, CPA, Promontory Strategy Group provides independent strategic and financial advisory services to privately held and family-owned businesses evaluating ownership transitions, acquisitions, and long-term growth initiatives.
We bring investment banking discipline and transaction experience to critical decisions and engage earlier in the process, before a formal transaction is underway. This allows owners and leadership teams to evaluate options with greater clarity, align stakeholders, and prepare thoughtfully rather than react under time pressure.
PSG works alongside a company’s existing trusted advisors: legal, accounting, and lending partners, providing an objective market perspective on valuation, capital structure, and transaction alternatives. Our role is to help translate strategy into executable plans that preserve flexibility and maximize long-term value.
In situations where timing, preparation, and alignment matter most, an experienced perspective applied early can materially influence outcomes.
If you are beginning to think about a business ownership transfer, engaging in pre-transaction advisory early can help you understand your options and prepare with intention.
By Christopher Riegg
Christopher Riegg is an investment banking professional with over three decades of experience providing strategic and financial guidance to business owners and executives. As a partner at Promontory Strategy Group, Christopher Riegg has worked with over 200 companies across various industries, including manufacturing, distribution, technology, and services. His focus areas include mergers and acquisitions, debt restructuring, recapitalization, and private equity capital.
